FAR Analysis
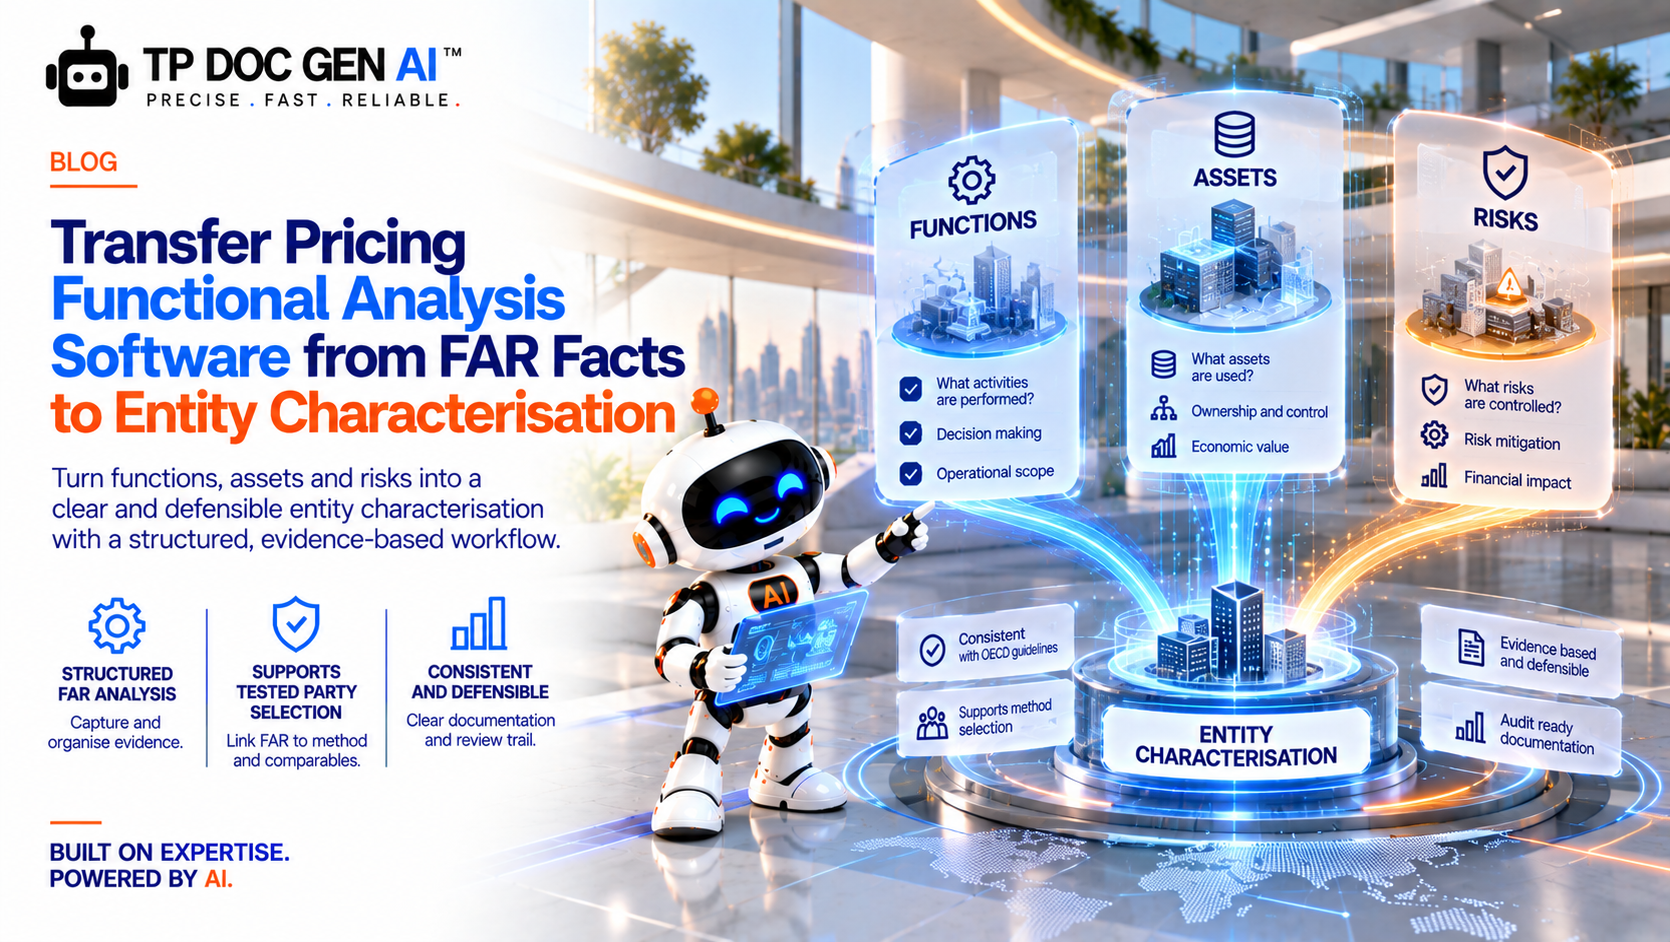
Transfer Pricing Functional Analysis Software from FAR Facts to Entity Characterisation
CA Mithilesh Reddy
24 Sept 2026 · 5 min read
Direct answer
Characterisation is a conclusion from actual conduct, capability, decision making and risk control. Software should structure evidence and inconsistencies; it should not select an archetype from a few labels. The professional conclusion should be based on current official material, reliable transaction data and a documented review trail. TP DOC GEN AI may organise and automate that workflow, while accountable professionals remain responsible for the legal interpretation, factual accuracy and filing decision.
The baseline technical framework should be checked against the OECD Transfer Pricing Guidelines 2022. Its role is to anchor the analysis in the current official position; the actual application still depends on the taxpayer, transaction, period and domestic rules.
What this guide covers
This guide explains a gated workflow that turns evidence about functions assets and risks into a supportable entity characterisation. It is written for finance leaders, tax teams, chartered accountancy and transfer pricing professionals, multinational groups and advisory firms. The central decision is whether the proposed characterisation follows the facts and supports method and tested party selection. The answers are intentionally self contained so search engines and answer engines can extract a useful response without losing the conditions that make it accurate.
The analysis is framed for Global. International guidance supplies a technical vocabulary, but domestic legislation, rules, forms and administrative instructions determine the legal obligation. Use the OECD guidance on transfer pricing documentation and country by country reporting together with the OECD transfer pricing country profiles to test both the general framework and the applicable local overlay. Every threshold, deadline, citation and form should be rechecked immediately before publication or filing. This article was source checked on 11 September 2026.
The professional framework
When building the control matrix, use the OECD country by country reporting resources to identify the separate filing, documentation or reporting purpose before data is reused. One source dataset may support several outputs, but each output needs its own scope, timing and approval.
| Workstream | Minimum evidence |
|---|---|
| Scope | Entity, jurisdiction, tax period, related party perimeter, transaction and statutory obligation |
| Facts | Contracts, interviews, decision rights, functions, assets, risks and actual conduct |
| Data | Ledger population, counterparty mapping, currencies, adjustments, segmental accounts and reconciliation |
| Analysis | Method, tested party, comparables, PLI, adjustments, range and conclusion |
| Control | Legal source, preparer, reviewer, exceptions, approval, filed version and retention |
Questions professionals ask first
What is functional analysis in transfer pricing
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to collect evidence from business personnel not only tax files. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Why is a questionnaire alone insufficient
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
For this part of the analysis, the official OECD toolkit on difficulties in accessing comparables data should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to distinguish risk bearing on paper from risk control in conduct. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should functions be evidenced
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
The practical control is to identify people and decision rights behind significant risks. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should assets be analysed
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to link assets and intangibles to value creating activities. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What does control over risk require
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
For this part of the analysis, the official OECD guidance on financial transactions should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to explain conflicts between contracts and behaviour. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How are contractual terms tested against conduct
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
The practical control is to make characterisation a reviewed output rather than an input label. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
When should the proposed characterisation be challenged
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
The practical control is to collect evidence from business personnel not only tax files. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How does characterisation affect the tested party
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
For this part of the analysis, the official OECD guidance for tax administrations on hard to value intangibles should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to distinguish risk bearing on paper from risk control in conduct. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How does it influence method selection
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to identify people and decision rights behind significant risks. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What should a FAR approval record contain
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
The practical control is to link assets and intangibles to value creating activities. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How often should FAR be refreshed
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
For this part of the analysis, the official OECD base erosion and profit shifting project should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to explain conflicts between contracts and behaviour. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How does TP DOC GEN AI structure FAR analysis
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
The practical control is to make characterisation a reviewed output rather than an input label. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What is the direct answer for a tax director
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to collect evidence from business personnel not only tax files. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Which legal and factual assumptions must be confirmed
Use the authority that governs the relevant jurisdiction and period, then test whether it actually supports the proposition in the document. For functional analysis characterisation tool, legislation, rules, forms and administrative guidance should be separated because their legal weight and effective dates differ.
The practical control is to distinguish risk bearing on paper from risk control in conduct. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What should finance provide to the transfer pricing team
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to identify people and decision rights behind significant risks. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What should the transfer pricing reviewer challenge
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
For this part of the analysis, the official OECD mutual agreement procedure statistics should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to link assets and intangibles to value creating activities. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should the controlled transaction be delineated
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to explain conflicts between contracts and behaviour. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should contracts be tested against actual conduct
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In functional analysis characterisation tool, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
The practical control is to make characterisation a reviewed output rather than an input label. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should the analysis reconcile to the accounts
Every material number should have a retained source, transformation rule, formula, reviewer and reconciliation. In functional analysis characterisation tool, a result is not controlled merely because the arithmetic is correct; the operating classifications, tested population, currency logic and sign conventions must also be supportable.
The practical control is to collect evidence from business personnel not only tax files. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Which professional judgements cannot be automated
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to distinguish risk bearing on paper from risk control in conduct. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What are the most common failure patterns
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For functional analysis characterisation tool, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
For this part of the analysis, the official United Nations practical manual on transfer pricing should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to identify people and decision rights behind significant risks. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What does an audit ready evidence trail contain
Audit readiness means another competent professional can reconstruct the filed position from retained evidence without relying on the original preparer's memory. For functional analysis characterisation tool, the pack should connect scope, facts, contracts, calculations, benchmarking, financial reconciliation, legal sources and approvals.
The practical control is to link assets and intangibles to value creating activities. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should changes after approval be managed
Start with a documented change assessment rather than an assumption that the prior answer remains valid. For functional analysis characterisation tool, changes in parties, transactions, functions, risk control, contracts, markets, financial definitions or law can alter the appropriate level of refresh.
The practical control is to explain conflicts between contracts and behaviour. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How often should the position be reviewed
Start with a documented change assessment rather than an assumption that the prior answer remains valid. For functional analysis characterisation tool, changes in parties, transactions, functions, risk control, contracts, markets, financial definitions or law can alter the appropriate level of refresh.
The practical control is to make characterisation a reviewed output rather than an input label. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Worked example
A group labels its subsidiary a limited risk distributor. Interviews show that local management sets discount bands, owns customer strategy and controls inventory decisions. The software must surface the conflict rather than repeat the policy label.
The team should not begin by drafting transfer pricing functional analysis software from far facts to entity characterisation. It should first create a scoped transaction and obligation register, obtain the documents that establish actual conduct, reconcile the financial population and record open assumptions. The technical analysis follows from that controlled fact base. Where data is incomplete, the report should identify the gap and owner rather than hide uncertainty behind fluent language.
The reviewer then reperforms one transaction from ledger to output, one FAR conclusion from interview evidence, one comparable from initial universe to final set, and one calculation from raw values to the reported result. Corrections are made in the source layer and regenerated through dependent outputs. The approved filed year is archived separately so the next rollover cannot overwrite the evidence that supported the original conclusion.
Implementation checklist
- Confirm the entity, jurisdiction, tax period, obligation, threshold and deadline from current official material
- Approve a complete related party and connected person population with unique counterparty identifiers
- Collect executed agreements and test their terms against actual operational conduct
- Document functions assets risks decision rights and the people who control material risks
- Map transaction values to the ledger and preserve currency aggregation adjustment and sign logic
- Record method selection tested party PLI comparables filters screening reasons and adjustments
- Reperform material calculations and resolve accounting identity or reconciliation failures
- Compare the return disclosure Local File Master File CbCR and counterparty treatment for consistency
- Record preparer reviewer exceptions resolution evidence approval date and exact approved version
- Archive official sources workpapers exports acknowledgements and retention responsibilities
How TP DOC GEN AI supports the workflow
TP DOC GEN AI is presented as an end to end transfer pricing documentation and benchmarking platform. Its TP DOC GEN AI product overview connects entity onboarding, transaction data, FAR, benchmarking, margin computation and report generation. The buyer should verify each relevant capability using an anonymised real case and documented acceptance criteria.
For this topic, review the integrated platform modules and ask the product specialist to trace inputs, rules, calculations, reviewer actions and exports. Treat the demonstration as a control test, not a substitute for tax advice or internal approval.
For this topic, review the OECD aligned methodology and ask the product specialist to trace inputs, rules, calculations, reviewer actions and exports. Treat the demonstration as a control test, not a substitute for tax advice or internal approval.
For this topic, review the transfer pricing documentation workflow and ask the product specialist to trace inputs, rules, calculations, reviewer actions and exports. Treat the demonstration as a control test, not a substitute for tax advice or internal approval.
For this topic, review the benchmarking and TP advisory workflow and ask the product specialist to trace inputs, rules, calculations, reviewer actions and exports. Treat the demonstration as a control test, not a substitute for tax advice or internal approval.
Next step book a personalised demo using an anonymised entity, transaction and jurisdiction that reflects the work your team actually performs. Ask to see the source trail, calculation controls, approvals and editable final output.
Developer publishing notes
Use the document title as the H1. Keep each question as an H2 or H3 and implement FAQPage structured data only for questions and answers visibly published on the page. Preserve contextual anchor text. Do not place the official links in a repetitive source block, and do not mark product claims as independent regulatory conclusions.
Suggested internal linking anchors are already embedded in the article. Before upload, the developer should verify redirects, use canonical URLs, open external sources in accordance with the site's policy, and ensure the Book a Demo link is measurable without changing the visible educational conclusion.
Conclusion
A defensible approach to functional analysis characterisation tool begins with the correct jurisdiction and period, moves through verified facts and reconciled data, and ends with a reviewable decision trail. The objective is not the longest document or fastest draft. It is a file that another professional can understand, reperform and update without guessing how the conclusion was reached.
TP DOC GEN AI can reduce mechanical work and connect evidence across the documentation lifecycle. Professional judgement remains essential for scope, characterisation, method selection, comparability, legal interpretation and final approval. That division of responsibility should be visible in both the workflow and the published explanation.
Editorial and professional disclaimer
This article provides general educational information and is not tax, legal, accounting or investment advice. Transfer pricing obligations and outcomes depend on the applicable law, tax year, jurisdiction and facts. Official material, deadlines, thresholds, forms and product functionality should be verified immediately before publication or use. Qualified advisers should review material decisions and filings.
More on FAR Analysis
FAR Analysis 13 Sept 2026 12 min read
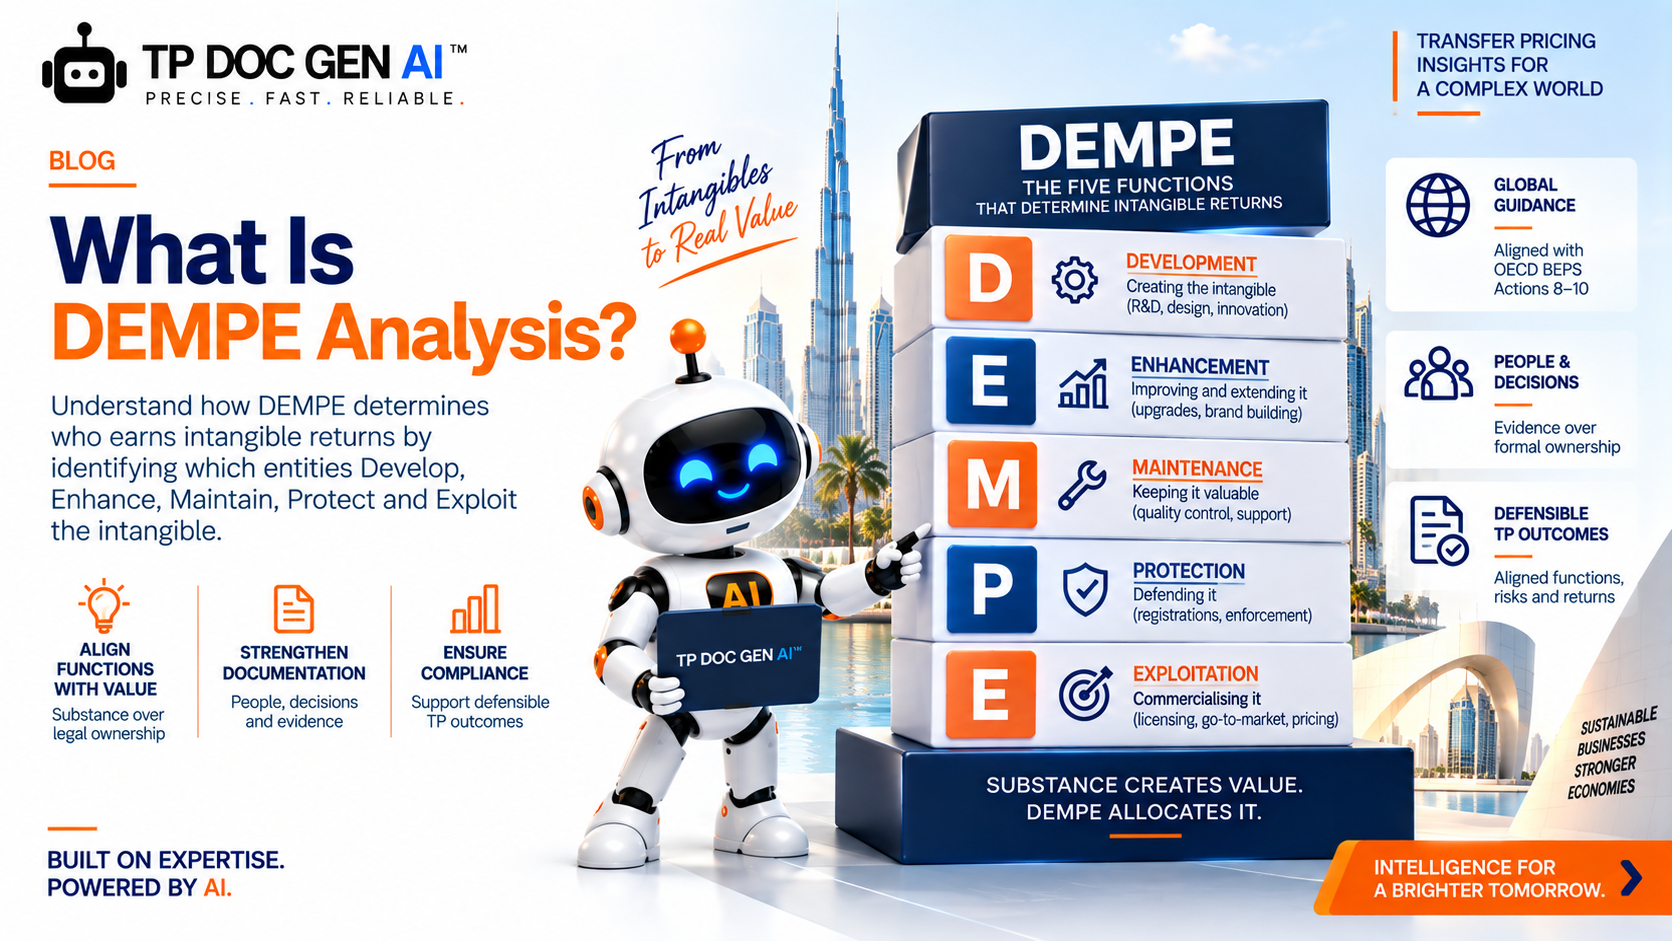
What Is DEMPE Analysis?
DEMPE analysis determines who earns intangible returns by identifying which entities Develop, Enhance, Maintain, Protect and Exploit the intangible - legal.
FAR Analysis 13 Sept 2026 12 min read
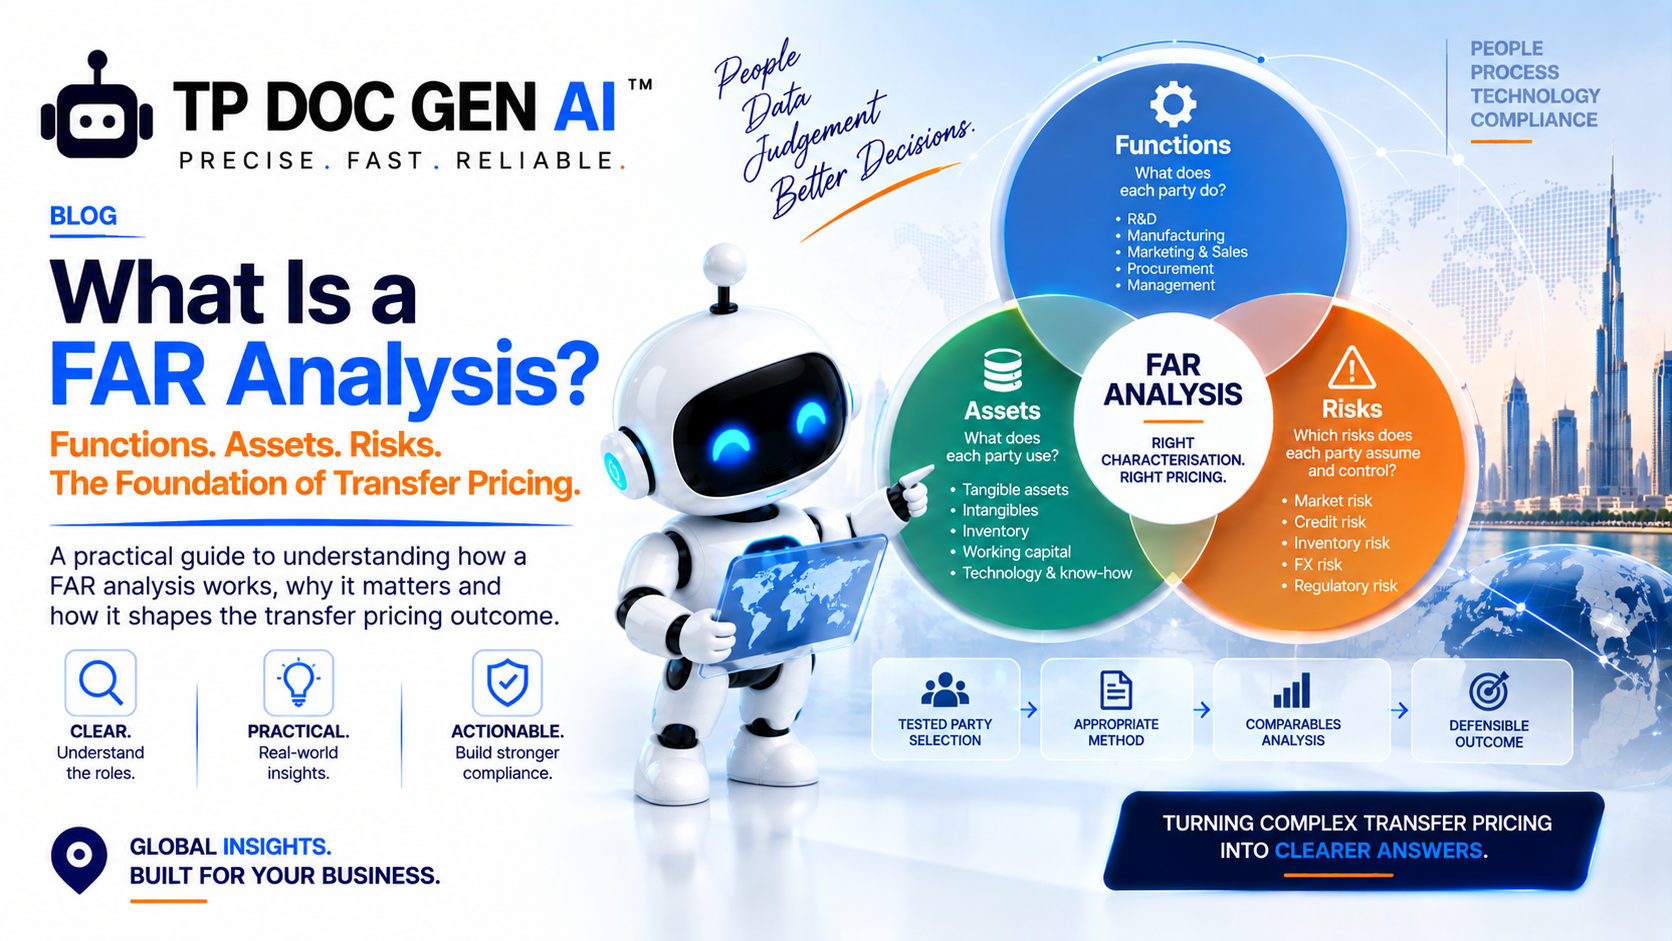
What Is a FAR Analysis?
A FAR analysis maps the functions performed, assets used and risks assumed by each party to a related-party transaction - the foundation of every transfer.