Benchmarking
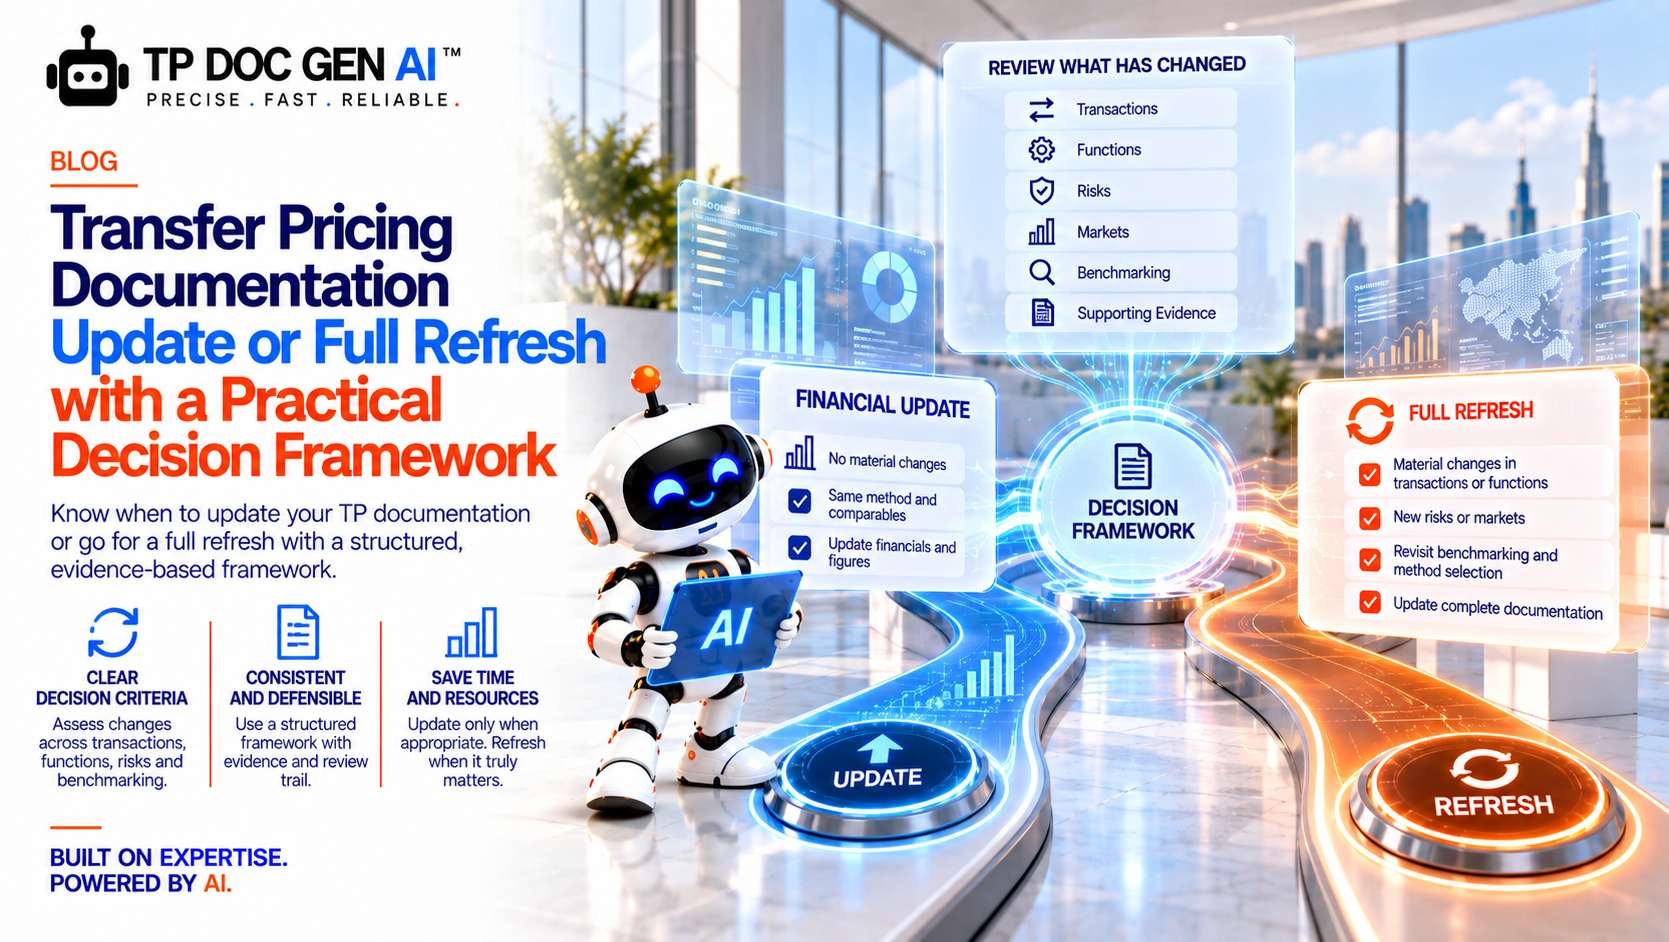
Transfer Pricing Documentation Update or Full Refresh with a Practical Decision Framework
CA Mithilesh Reddy
27 Sept 2026 · 5 min read
Direct answer
A financial update is appropriate only when the controlled transaction, parties, functions, risks, method, market and comparable set remain sufficiently reliable. The drafting date or budget pressure cannot decide the scope. The professional conclusion should be based on current official material, reliable transaction data and a documented review trail. TP DOC GEN AI may organise and automate that workflow, while accountable professionals remain responsible for the legal interpretation, factual accuracy and filing decision.
The baseline technical framework should be checked against the UAE Federal Tax Authority Transfer Pricing Guide. Its role is to anchor the analysis in the current official position; the actual application still depends on the taxpayer, transaction, period and domestic rules.
What this guide covers
This guide explains the decision between a financial update and a full factual and economic refresh. It is written for finance leaders, tax teams, chartered accountancy and transfer pricing professionals, multinational groups and advisory firms. The central decision is what has changed since the earlier study and whether those changes undermine its conclusion. The answers are intentionally self contained so search engines and answer engines can extract a useful response without losing the conditions that make it accurate.
The analysis is framed for Global. International guidance supplies a technical vocabulary, but domestic legislation, rules, forms and administrative instructions determine the legal obligation. Use the UAE Ministry of Finance Transfer Pricing Documentation Decision together with the India Income Tax Department Transfer Pricing guidance to test both the general framework and the applicable local overlay. Every threshold, deadline, citation and form should be rechecked immediately before publication or filing. This article was source checked on 11 September 2026.
The professional framework
When building the control matrix, use the UAE Ministry of Finance Country-by-Country Reporting to identify the separate filing, documentation or reporting purpose before data is reused. One source dataset may support several outputs, but each output needs its own scope, timing and approval.
| Workstream | Minimum evidence |
|---|---|
| Scope | Entity, jurisdiction, tax period, related party perimeter, transaction and statutory obligation |
| Facts | Contracts, interviews, decision rights, functions, assets, risks and actual conduct |
| Data | Ledger population, counterparty mapping, currencies, adjustments, segmental accounts and reconciliation |
| Analysis | Method, tested party, comparables, PLI, adjustments, range and conclusion |
| Control | Legal source, preparer, reviewer, exceptions, approval, filed version and retention |
Questions professionals ask first
What is a transfer pricing financial update
Every material number should have a retained source, transformation rule, formula, reviewer and reconciliation. In when to update transfer pricing benchmarking, a result is not controlled merely because the arithmetic is correct; the operating classifications, tested population, currency logic and sign conventions must also be supportable.
The practical control is to begin with a documented change questionnaire. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What is a full refresh
Start with a documented change assessment rather than an assumption that the prior answer remains valid. For when to update transfer pricing benchmarking, changes in parties, transactions, functions, risk control, contracts, markets, financial definitions or law can alter the appropriate level of refresh.
For this part of the analysis, the official India Income Tax Department transfer pricing and comparability guidance should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to separate factual changes from data updates. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Which changes require a new FAR analysis
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In when to update transfer pricing benchmarking, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
The practical control is to retest comparability when markets or business models shift. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
When should benchmarking be refreshed
A defensible benchmarking result begins with the accurately delineated transaction and ends with a reproducible final set. For when to update transfer pricing benchmarking, preserve the database universe, search date, filters, source financials, accept reject reasons, adjustments and statistical computation rather than only the final range.
The practical control is to reconcile new financials using the same definitions. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Can the prior comparable set be reused
A defensible benchmarking result begins with the accurately delineated transaction and ends with a reproducible final set. For when to update transfer pricing benchmarking, preserve the database universe, search date, filters, source financials, accept reject reasons, adjustments and statistical computation rather than only the final range.
For this part of the analysis, the official UAE Federal Tax Authority Transfer Pricing Guide should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to preserve the previous filed year before updating. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should market changes be assessed
Start with a documented change assessment rather than an assumption that the prior answer remains valid. For when to update transfer pricing benchmarking, changes in parties, transactions, functions, risk control, contracts, markets, financial definitions or law can alter the appropriate level of refresh.
The practical control is to record the decision rule and reviewer approval. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What if only financial classifications changed
Every material number should have a retained source, transformation rule, formula, reviewer and reconciliation. In when to update transfer pricing benchmarking, a result is not controlled merely because the arithmetic is correct; the operating classifications, tested population, currency logic and sign conventions must also be supportable.
The practical control is to begin with a documented change questionnaire. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should restructurings affect the decision
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For when to update transfer pricing benchmarking, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
For this part of the analysis, the official India Income Tax Department Transfer Pricing guidance should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to separate factual changes from data updates. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What evidence supports a no change conclusion
Audit readiness means another competent professional can reconstruct the filed position from retained evidence without relying on the original preparer's memory. For when to update transfer pricing benchmarking, the pack should connect scope, facts, contracts, calculations, benchmarking, financial reconciliation, legal sources and approvals.
The practical control is to retest comparability when markets or business models shift. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Who should approve the update scope
Start with a documented change assessment rather than an assumption that the prior answer remains valid. For when to update transfer pricing benchmarking, changes in parties, transactions, functions, risk control, contracts, markets, financial definitions or law can alter the appropriate level of refresh.
The practical control is to reconcile new financials using the same definitions. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should prior filed versions be preserved
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For when to update transfer pricing benchmarking, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
For this part of the analysis, the official India CBDT Country-by-Country Reporting information should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to preserve the previous filed year before updating. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How does TP DOC GEN AI manage rollover controls
TP DOC GEN AI can support the controlled production layer for when to update transfer pricing benchmarking by connecting structured entity data, transactions, FAR, benchmarking, deterministic calculations, documentation and reviewer workflows. It does not remove the need for professional judgement or legal verification.
The practical control is to record the decision rule and reviewer approval. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What is the direct answer for a tax director
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For when to update transfer pricing benchmarking, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to begin with a documented change questionnaire. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Which legal and factual assumptions must be confirmed
Use the authority that governs the relevant jurisdiction and period, then test whether it actually supports the proposition in the document. For when to update transfer pricing benchmarking, legislation, rules, forms and administrative guidance should be separated because their legal weight and effective dates differ.
The practical control is to separate factual changes from data updates. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What should finance provide to the transfer pricing team
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For when to update transfer pricing benchmarking, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to retest comparability when markets or business models shift. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What should the transfer pricing reviewer challenge
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For when to update transfer pricing benchmarking, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
For this part of the analysis, the official UAE Ministry of Finance Mutual Agreement Procedure guidance should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to reconcile new financials using the same definitions. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should the controlled transaction be delineated
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For when to update transfer pricing benchmarking, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to preserve the previous filed year before updating. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should contracts be tested against actual conduct
Functional analysis must describe what people actually do, which assets support those activities and who has capability and authority to control economically significant risks. In when to update transfer pricing benchmarking, contracts are the starting point; interviews, approvals and operating evidence determine whether conduct supports the stated characterisation.
The practical control is to record the decision rule and reviewer approval. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should the analysis reconcile to the accounts
Every material number should have a retained source, transformation rule, formula, reviewer and reconciliation. In when to update transfer pricing benchmarking, a result is not controlled merely because the arithmetic is correct; the operating classifications, tested population, currency logic and sign conventions must also be supportable.
The practical control is to begin with a documented change questionnaire. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Which professional judgements cannot be automated
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For when to update transfer pricing benchmarking, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
The practical control is to separate factual changes from data updates. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What are the most common failure patterns
The direct answer depends on the relevant entity, transaction, period, jurisdiction and evidence. For when to update transfer pricing benchmarking, the responsible professional should state these assumptions before reaching a conclusion and should avoid converting a general principle into a universal rule.
For this part of the analysis, the official India Income Tax Department Transfer Pricing documentation guidance should be read with the facts and period stated above. The source should be retained with its access date because a later update may be relevant to a new year without changing the basis used for an earlier filed position.
The practical control is to retest comparability when markets or business models shift. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
What does an audit ready evidence trail contain
Audit readiness means another competent professional can reconstruct the filed position from retained evidence without relying on the original preparer's memory. For when to update transfer pricing benchmarking, the pack should connect scope, facts, contracts, calculations, benchmarking, financial reconciliation, legal sources and approvals.
The practical control is to reconcile new financials using the same definitions. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How should changes after approval be managed
Start with a documented change assessment rather than an assumption that the prior answer remains valid. For when to update transfer pricing benchmarking, changes in parties, transactions, functions, risk control, contracts, markets, financial definitions or law can alter the appropriate level of refresh.
The practical control is to preserve the previous filed year before updating. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
How often should the position be reviewed
Start with a documented change assessment rather than an assumption that the prior answer remains valid. For when to update transfer pricing benchmarking, changes in parties, transactions, functions, risk control, contracts, markets, financial definitions or law can alter the appropriate level of refresh.
The practical control is to record the decision rule and reviewer approval. Record the owner, supporting evidence, unresolved items, reviewer and each output affected. Resolve contradictions before approving the narrative, calculation or form, and retain the approved decision with the filed year record.
Worked example
A contract manufacturer has stable ownership and products, but a restructuring moved procurement and inventory decisions to the local entity. Finance proposes a numeric rollover because the database set is only one year old.
The team should not begin by drafting transfer pricing documentation update or full refresh with a practical decision framework. It should first create a scoped transaction and obligation register, obtain the documents that establish actual conduct, reconcile the financial population and record open assumptions. The technical analysis follows from that controlled fact base. Where data is incomplete, the report should identify the gap and owner rather than hide uncertainty behind fluent language.
The reviewer then reperforms one transaction from ledger to output, one FAR conclusion from interview evidence, one comparable from initial universe to final set, and one calculation from raw values to the reported result. Corrections are made in the source layer and regenerated through dependent outputs. The approved filed year is archived separately so the next rollover cannot overwrite the evidence that supported the original conclusion.
Implementation checklist
- Confirm the entity, jurisdiction, tax period, obligation, threshold and deadline from current official material
- Approve a complete related party and connected person population with unique counterparty identifiers
- Collect executed agreements and test their terms against actual operational conduct
- Document functions assets risks decision rights and the people who control material risks
- Map transaction values to the ledger and preserve currency aggregation adjustment and sign logic
- Record method selection tested party PLI comparables filters screening reasons and adjustments
- Reperform material calculations and resolve accounting identity or reconciliation failures
- Compare the return disclosure Local File Master File CbCR and counterparty treatment for consistency
- Record preparer reviewer exceptions resolution evidence approval date and exact approved version
- Archive official sources workpapers exports acknowledgements and retention responsibilities
How TP DOC GEN AI supports the workflow
TP DOC GEN AI is presented as an end to end transfer pricing documentation and benchmarking platform. Its TP DOC GEN AI product overview connects entity onboarding, transaction data, FAR, benchmarking, margin computation and report generation. The buyer should verify each relevant capability using an anonymised real case and documented acceptance criteria.
For this topic, review the transfer pricing documentation workflow and ask the product specialist to trace inputs, rules, calculations, reviewer actions and exports. Treat the demonstration as a control test, not a substitute for tax advice or internal approval.
For this topic, review the benchmarking and TP advisory workflow and ask the product specialist to trace inputs, rules, calculations, reviewer actions and exports. Treat the demonstration as a control test, not a substitute for tax advice or internal approval.
For this topic, review the integrated platform modules and ask the product specialist to trace inputs, rules, calculations, reviewer actions and exports. Treat the demonstration as a control test, not a substitute for tax advice or internal approval.
For this topic, review the audit and litigation support workflow and ask the product specialist to trace inputs, rules, calculations, reviewer actions and exports. Treat the demonstration as a control test, not a substitute for tax advice or internal approval.
Next step book a personalised demo using an anonymised entity, transaction and jurisdiction that reflects the work your team actually performs. Ask to see the source trail, calculation controls, approvals and editable final output.
Developer publishing notes
Use the document title as the H1. Keep each question as an H2 or H3 and implement FAQPage structured data only for questions and answers visibly published on the page. Preserve contextual anchor text. Do not place the official links in a repetitive source block, and do not mark product claims as independent regulatory conclusions.
Suggested internal linking anchors are already embedded in the article. Before upload, the developer should verify redirects, use canonical URLs, open external sources in accordance with the site's policy, and ensure the Book a Demo link is measurable without changing the visible educational conclusion.
Conclusion
A defensible approach to when to update transfer pricing benchmarking begins with the correct jurisdiction and period, moves through verified facts and reconciled data, and ends with a reviewable decision trail. The objective is not the longest document or fastest draft. It is a file that another professional can understand, reperform and update without guessing how the conclusion was reached.
TP DOC GEN AI can reduce mechanical work and connect evidence across the documentation lifecycle. Professional judgement remains essential for scope, characterisation, method selection, comparability, legal interpretation and final approval. That division of responsibility should be visible in both the workflow and the published explanation.
Editorial and professional disclaimer
This article provides general educational information and is not tax, legal, accounting or investment advice. Transfer pricing obligations and outcomes depend on the applicable law, tax year, jurisdiction and facts. Official material, deadlines, thresholds, forms and product functionality should be verified immediately before publication or use. Qualified advisers should review material decisions and filings.
More on Benchmarking
Benchmarking 24 Sept 2026 5 min read
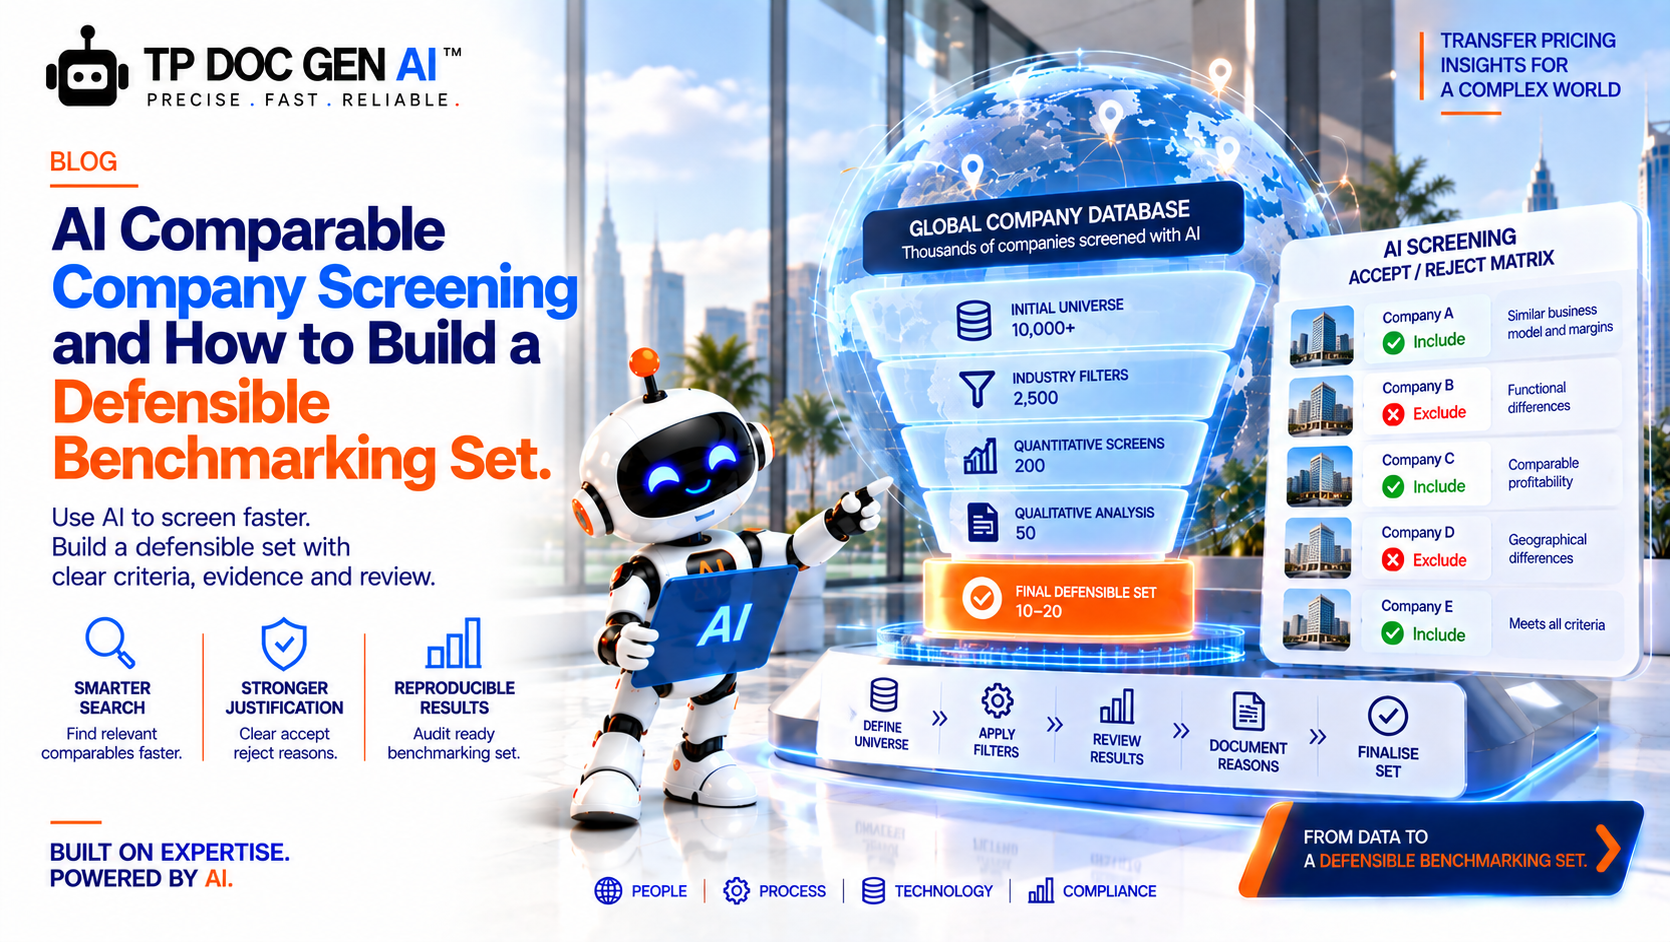
AI Comparable Company Screening and How to Build a Defensible Benchmarking Set
Learn how AI can support comparable company screening in transfer pricing while maintaining a defensible benchmarking process. This guide explains quantitative and qualitative screening, comparability factors, accept-reject reasoning, review controls, evidence trails and the role of professional judgement in building a reproducible final set.
Benchmarking 13 Sept 2026 13 min read
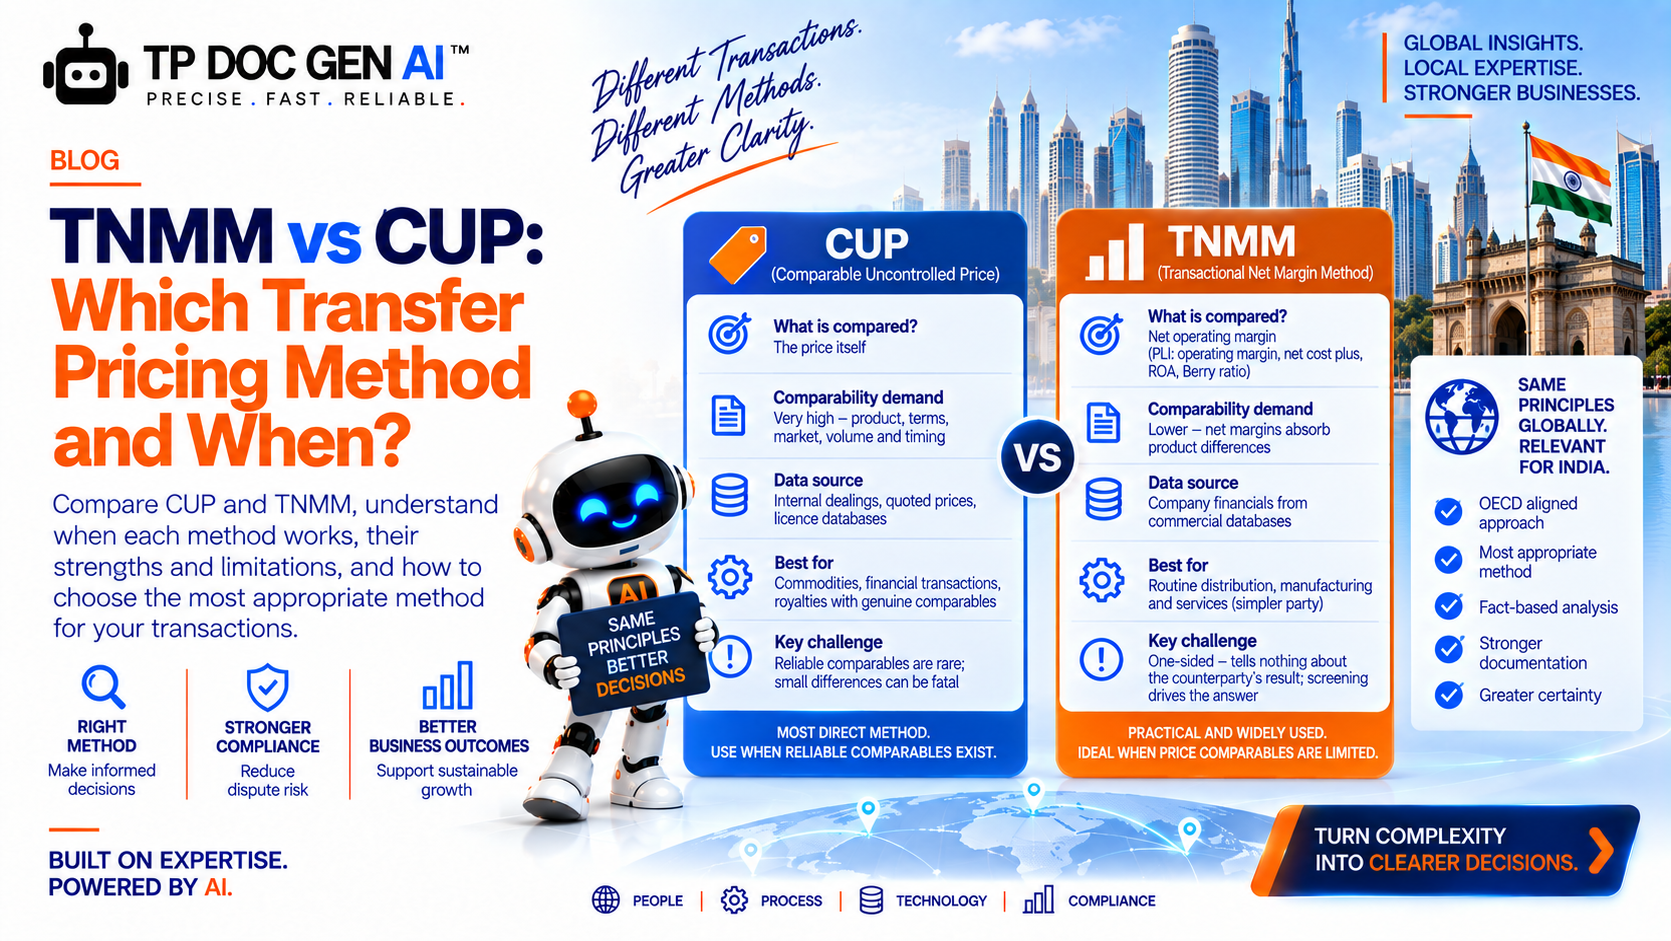
TNMM vs CUP: Which Transfer Pricing Method and When?
CUP compares prices; TNMM compares net margins. When each method wins, why CUP ranks first but TNMM dominates practice, and the comparability trade-off.
Benchmarking 13 Sept 2026 12 min read
What Is Benchmarking in Transfer Pricing?
Transfer pricing benchmarking is the search for comparable independent transactions or companies used to establish the arm's length range for a.