What Is the Saudi Arabia TP Documentation Threshold?
CA Mithilesh Reddy
13 Sept 2026 · 12 min read
On this page
Direct answer
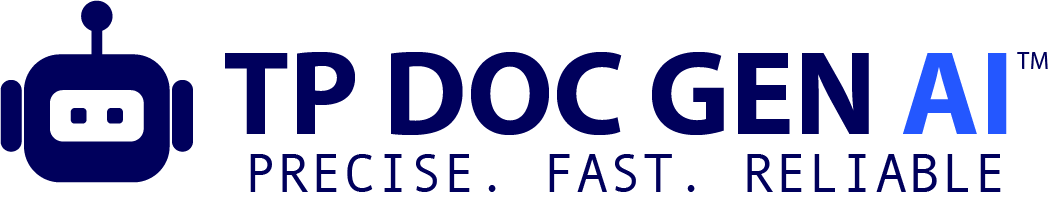
Under the ZATCA Transfer Pricing Bylaws, income tax payers in Saudi Arabia must maintain a Master File and Local File where the aggregate arm's length value of their controlled transactions exceeds SAR 6 million in a 12-month period. Zakat payers phase in at SAR 100 million of controlled transactions for FY2024–FY2026, with the threshold dropping to SAR 48 million from FY2027. The underlying framework can be reviewed in the Transfer Pricing Regulations.
Why this question matters
What Is the Saudi Arabia TP Documentation Threshold? is not only a definition or filing question. It affects how a multinational group captures transactions, allocates responsibility, prepares financial data and responds when a tax authority asks for evidence. The key professional issue is taxpayer status, controlled-transaction aggregation, zakat phase-in and the distinction between disclosure and file thresholds. A technically correct rule can still be applied badly when the facts, accounting records and documentation workflow are disconnected. For the official position, refer to ZATCA Transfer Pricing FAQs.
The analysis in this article is framed for Saudi Arabia. OECD materials provide a common technical language, but local legislation, rules, forms and administrative guidance govern the legal obligation. Thresholds and deadlines are therefore presented with a verification date and should be reconfirmed before a filing or transaction decision. Additional authoritative context is available in Tax Rules and Regulations.
The thresholds at a glance (as at August 2026)
| Obligation | Taxpayer type | Threshold |
|---|---|---|
| Disclosure Form + CPA affidavit | All persons subject to the Bylaws with related-party dealings | No value threshold - filed with the return within 120 days of year end |
| Master File + Local File | Income tax payers | Controlled transactions > SAR 6m |
| Master File + Local File | Zakat payers | ≥ SAR 100m (FY2024–26); ≥ SAR 48m from FY2027 |
| CbCR | All MNE groups | Consolidated revenue ≥ SAR 3.2bn |
| Local File production | All in scope | Within 30 days of ZATCA request |
Reading the numbers correctly
- SAR 6m is low by design - for corporate income tax payers, documentation is effectively universal wherever related-party dealings are material at all.
- The zakat phase-in is the big shift. Family groups and holding structures wholly subject to zakat, historically outside documentation entirely, entered the regime from fiscal years beginning 1 January 2024; the FY2027 drop to SAR 48m roughly doubles the captured population again.
- The value tested is the arm's length value of controlled transactions aggregated over the 12-month period - not entity revenue.
- The disclosure layer has no threshold. Even below the file thresholds, the Controlled Transactions Disclosure Form and the CPA affidavit - a licensed auditor certifying consistent transfer pricing policy - apply, which keeps every filing professionally certified.
What sub-threshold entities still owe
The arm's length principle applies regardless: ZATCA can examine any related-party pricing, adjustments cascade into withholding tax and zakat bases, and the affidavit signed each year presumes a policy that actually exists. A proportionate pricing file - policy, functional summary, regional benchmarking support - is the sensible floor below the formal thresholds. The underlying framework can be reviewed in the Information Exchange Portal.
FAQ
Are natural persons and small enterprises exempt? The Bylaws exempt natural persons and qualifying small enterprises from the documentation requirements; the arm's length standard still governs any in-scope dealings. For the official position, refer to OECD Transfer Pricing Guidelines 2022.
Do mixed zakat/tax groups apply which threshold? Per entity, by its own status - a group can have income tax members at SAR 6m and zakat members on the phased thresholds simultaneously, which is exactly where domestic transactions become documentable. Additional authoritative context is available in BEPS Action 13: Transfer Pricing Documentation and CbCR.
How fast must the Local File be produced? Within 30 days of a ZATCA request - contemporaneous preparation is the only workable model.
Which comparables does ZATCA accept? Regional GCC/MENA sets are standard practice, with the screening criteria documented and reproducible.
How should the issue be handled in practice?
Step 1: Identify the obligation
Map every entity to its taxpayer status, related-party population, relevant threshold and form. Treat documentation, disclosure, notification and filing as separate obligations even when they use common data. For Saudi Arabia transfer pricing documentation threshold, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved. The underlying framework can be reviewed in the Transfer Pricing Country Profiles.
Step 2: Resolve the deadline from the fiscal year end
Do not use a generic group calendar date. Compute the deadline under the jurisdiction's rule and retain the legal source and version used. For Saudi Arabia transfer pricing documentation threshold, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved.
Step 3: Assign accountable owners
Give legal, finance, tax and business teams defined inputs and internal due dates. Missing information should have an escalation owner rather than remaining an unrecorded assumption. For Saudi Arabia transfer pricing documentation threshold, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved.
Step 4: Reconcile before submission
Tie transaction values, entity names, methods and outcomes across the accounts, return, disclosure, Local File, Master File and CbCR. Explain legitimate differences with a documented bridge. For Saudi Arabia transfer pricing documentation threshold, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved.
Step 5: Preserve proof of compliance
Archive the filed form, acknowledgement, exact supporting file, source calculations and approvals. Calendar completion is not enough if the organisation cannot later produce what was filed. For Saudi Arabia transfer pricing documentation threshold, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved.
Worked example
A Saudi group contains both income-tax and zakat-paying entities. Applying one group-level threshold can produce the wrong answer because the taxpayer category and applicable phase-in must be tested entity by entity. The controlled-transaction population and disclosure obligations must then be reconciled to the return. For the official position, refer to UN Practical Manual on Transfer Pricing 2021.
The example does not establish a universal answer. It shows why the sequence matters: define scope, establish conduct, apply the local rule, perform the economic analysis, reconcile the figures and document the review. If one of those links changes, the conclusion may also change.
What will a senior transfer-pricing reviewer challenge?
Thresholds should be evidenced through a signed workpaper that identifies the tested amount, aggregation rule, taxpayer status, period and legal source. A conclusion copied into an email is not a sufficient control for a recurring obligation.
The reviewer will test the boundary cases: deemed transactions, zero-charge arrangements, guarantees, permanent establishments, changes in year end, short periods and different accounting currencies. These items frequently sit outside routine ledger extracts.
A compliance calendar is only effective when linked to deliverables and evidence. Every completed row should point to the final form, acknowledgement, source file and responsible reviewer.
Evidence and documentation checklist
- Scope memorandum: Entity, period, jurisdiction, transaction or obligation, threshold test and exclusions, with the current legal source recorded.
- Legal and ownership records: Entity chart, related-party analysis, permanent-establishment mapping and relevant registrations or taxpayer classifications.
- Executed agreements: Contracts, amendments, pricing schedules, service descriptions, licence terms, financing terms and evidence that conduct followed the agreed framework.
- Transaction register: Counterparty, amount, currency, invoice or journal source, method, owner and reconciliation status for each controlled flow.
- Functional evidence: Interview notes, organisation charts, approval matrices and documents showing who performed functions, used assets and controlled risks.
- Economic workpapers: Method memorandum, database query, filters, comparable accept-reject matrix, adjustments, PLI or valuation calculations and range.
- Financial bridge: Reconciliation from audited or reliable accounts to transaction values, segmental results, operating classifications and the tested outcome.
- Cross-report consistency check: Comparison with the tax return, disclosure form, Local File, Master File, CbCR and counterparty treatment, with differences explained.
- Review and approvals: Preparer, reviewer, unresolved assumptions, resolution evidence, sign-off date and the exact version approved for filing or submission.
- Filing and retention evidence: Submission acknowledgement, correspondence, authority requests, response index and a retention period aligned with local law.
Common failure patterns
- Treating Saudi Arabia transfer pricing documentation threshold as a wording exercise instead of linking the conclusion to contracts, conduct and accounts.
- Using a global policy without documenting the local legal overlay, threshold, form, deadline or language requirement.
- Rolling forward the previous year without testing changes in entities, transactions, people functions, risks, markets and accounting classifications.
- Presenting precise calculations without preserving source data, screening decisions, assumptions and a financial reconciliation.
- Allowing the Local File, disclosure form, return, Master File, CbCR or counterparty documentation to use different transaction populations without an explanation.
- Treating AI-generated drafting as professional approval, or making absolute product claims that are not supported by the facts and controls.
How TP DOC GEN AI can support this work
TP DOC GEN AI brings the transaction register, documentation workflow and jurisdiction-linked compliance calendar into the same operating model. Teams can connect due dates to the file, maintain source URLs and preserve the evidence behind benchmarking and reporting. The platform assists preparation and control; filing, legal advice, authority negotiation and accountable approval remain with the taxpayer and its advisers.
Relevant product page: See the TP DOC GEN AI workflow. The most useful demonstration is an anonymised scenario that mirrors the entity, transaction and jurisdiction your team actually handles.
Next step: Book a personalised demo and ask the specialist to show the source trail, calculation controls, reviewer workflow and final Word/PDF output.
Additional questions professionals frequently ask
Does being below a documentation threshold remove the arm's length rule?
Generally no. Thresholds often determine the form or depth of prescribed documentation, while the substantive arm's length principle and record-keeping obligations can still apply.
Should thresholds be tested by entity or group?
It depends on the specific obligation. Some use entity revenue or transaction value; Master File and CbCR rules may use group revenue. Test each obligation separately.
Can one calendar date be used across the group?
No. Deadlines may depend on entity fiscal year end, return date, taxpayer status and jurisdiction. Resolve dates entity by entity.
What is the best compliance control?
One approved transaction and obligation register linked to legal sources, owners, due dates, deliverables, reconciliations and filing evidence.
What is the first practical step for Saudi Arabia transfer pricing documentation threshold?
Define the exact entity, transaction or obligation and governed period. Then identify the official rule, responsible business owner, required source records and deadline. Starting with a template before scope is settled usually creates rework and hides omissions.
How should a multinational group govern Saudi Arabia transfer pricing documentation threshold?
Use a group framework for definitions, data and review, but document local overlays for Saudi Arabia. Maintain one approved transaction population, a jurisdiction-specific obligation register and a controlled process for exceptions.
Where should professional judgement be recorded?
In the working papers and final narrative wherever facts are interpreted, alternatives are rejected, comparability adjustments are made or a legal threshold is applied. The record should identify the evidence, reasoning, reviewer and date.
How can the content remain useful after publication?
Show the last-verified date, link directly to official authorities, avoid absolute claims that depend on facts and schedule a periodic regulatory review. This also improves trust for search engines and answer engines.
Practitioner's implementation notes
From a finance-function perspective, Saudi Arabia transfer pricing documentation threshold should not sit in a tax-only folder. The underlying transaction originates in contracts, operating decisions and accounting systems. Tax can analyse the position only when legal, finance and business owners provide a common description and agree how the numbers are extracted.
For Saudi Arabia, the official source should be retained with an access or verification date because webpages, forms and administrative guidance can change. When the law changes, update the current-year workpaper while preserving the source used for an earlier filing. Version control is part of technical accuracy.
AEO and GEO visibility depend on answer quality, not merely question-shaped headings. Each answer should be self-contained, identify the jurisdiction and period, distinguish a general principle from a filing rule, and link to the primary authority. This makes the page easier for professionals, search engines and AI answer systems to interpret.
The practical standard for Saudi Arabia transfer pricing documentation threshold is reproducibility. A reviewer who was not involved in preparation should be able to locate the source facts, understand the judgement, reperform the material calculation and identify the final approved output without relying on the original preparer's memory.
Management information should also track exceptions: transactions without agreements, entities with changed functions, missing segmental accounts, unreconciled disclosure values, stale comparable searches and deadlines without an owner. An exception register converts a long report into an operating control.
Finally, materiality should guide effort but should not be confused with legal scope. A low-value item may require disclosure even when extensive benchmarking is disproportionate, while a high-value recurring flow may justify deeper analysis, bilateral certainty or more frequent monitoring. Record both the legal requirement and the risk-based response.
Conclusion
A defensible position on Saudi Arabia transfer pricing documentation threshold combines current law, verified facts, reliable analysis, reconciled financial information and an accountable review trail. The goal is not simply to produce a long document. It is to create a record that another professional can understand, reperform and defend after the people and systems involved have changed. Additional authoritative context is available in Toolkit for Transfer Pricing Documentation Requirements.
Editorial and professional disclaimer
This article provides general educational information and is not tax, legal, accounting or investment advice. Transfer-pricing outcomes depend on the applicable law, tax year, jurisdiction and facts. Qualified advisers should be consulted before filing or adopting a position.
More on Compliance
MCP Server Transfer Pricing: What an MCP Server Is and Why a Platform Offers One
22 Oct 2026 5 min read
Transfer Pricing Practice Management: Roles, Permissions and Oversight for CA Firms Running Multiple Engagements
17 Oct 2026 5 min read
Form 3CEB Automation from the Local File to the Accountants Report
27 Sept 2026 5 min read